A Simple Guide to Protecting the Work You Create
When you are just starting out as an artist, insurance may be one of the last things on your mind.
You are thinking about materials, studio space, exhibitions, pricing, and hopefully selling your work. Insurance and appraisals can sound like things that only established artists or expensive art collectors need to worry about.
But as your body of work grows, something changes.
You may have thousands of dollars’ worth of finished artwork sitting in your home or studio. Some pieces may be at a gallery. Others may be packed for an exhibition or waiting to be shipped to a buyer.
At that point, it is worth asking a simple question:
If something happened to my artwork tomorrow, would I know exactly what I lost, and would my insurance cover it?
The answer is not always as simple as artists expect.
Your Homeowners Insurance May Not Cover Everything
If you work from a home studio, it is easy to assume that your homeowners or renters insurance automatically protects your artwork, supplies, equipment, and finished inventory.
That assumption can be risky.
Standard homeowners policies may provide limited coverage for property used for business purposes, and business-related liability may also require separate coverage. The Insurance Information Institute recommends that people running businesses from home review whether they need a homeowners endorsement, an in-home business policy, or a business owners policy (BOP), depending on their situation.
For an artist, that means you shouldn’t assume every painting, sculpture, ceramic piece, photograph, tool, or finished work in your studio is fully protected just because it’s inside your house.
Ask your insurance agent specifically about artwork you create and intend to sell.
That distinction matters.
Think About Where Your Artwork Goes
Your artwork does not always stay safely in your studio.
A piece might be:
- stored at home or in your studio
- delivered to a gallery
- displayed at an exhibition or art fair
- temporarily loaned
- placed on consignment
- stored somewhere else
- shipped to a customer
- transported in your own vehicle
Coverage that applies while artwork is sitting in your studio may not necessarily work the same way when the artwork leaves the premises.
Before sending valuable work somewhere, find out who is responsible for it and when that responsibility begins and ends.
For example, if a gallery is exhibiting your work, don’t simply assume that the gallery’s insurance covers every possible loss. Ask what coverage exists and review your consignment or exhibition agreement.
What Is an Art Appraisal?
An appraisal is a professional opinion of value prepared for a particular purpose.
And this is where things can become confusing.
There isn’t simply one universal “value” for a piece of artwork.
An artwork can have different values depending on why you’re valuing it. For example, retail replacement value used for certain insurance purposes can differ from fair market value. Chubb notes that retail replacement value is generally used for insurance scheduling and can include costs to replace an item, while fair market value reflects a different type of market transaction.
This is one reason an artist shouldn’t assume:
“I priced this painting at $3,000, so its insurance value must be $3,000.”
Your asking price, previous selling prices, market history, and the valuation an insurer accepts are related, but not necessarily the same.
Does Every Artist Need a Professional Appraisal?
No.
You do not necessarily need to hire an appraiser for every piece you create.
Insurance companies have different documentation and appraisal requirements. For example, Chubb says its personal fine-art policy requires professional appraisals only for individual fine-art items at or above a specified high-value threshold; below that threshold, it may accept a detailed description and estimated value. That is one insurer’s policy, not a general rule for artists.
For emerging artists whose work does not yet have an established secondary market, maintaining good records may initially be far more useful than trying to obtain formal appraisals for every new piece.
If your work becomes more valuable, your sales history develops, or your insurer requests an appraisal, you can discuss whether a qualified art appraiser is appropriate.
Start With Good Records
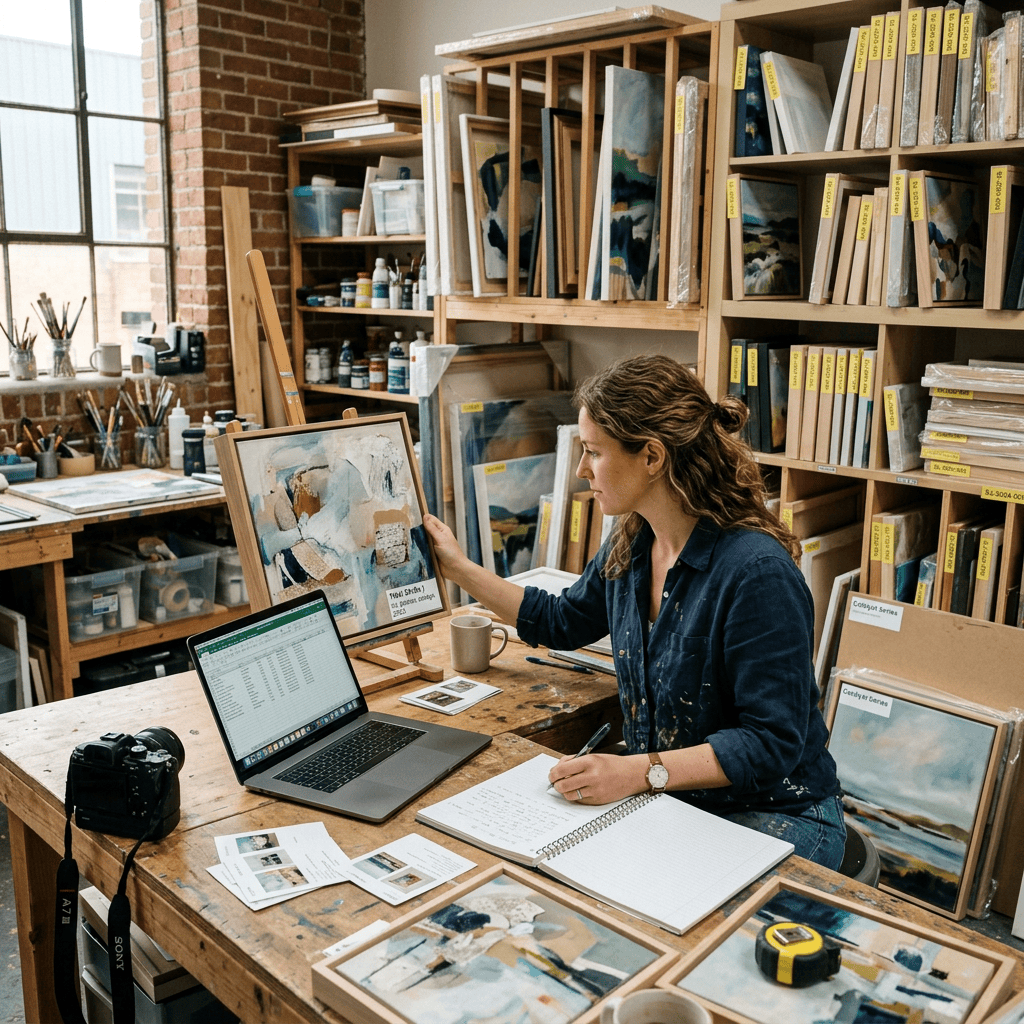
This is where studio inventory management becomes surprisingly important.
Imagine that a fire, hurricane, water leak, theft, or another covered event damages several years of your artwork.
Could you produce a list of exactly what was there?
For each finished piece, try to keep:
Artwork title
Inventory number
Year completed
Medium/materials
Dimensions
Clear photographs
Original asking price
Actual sale price, if sold
Current location
Exhibition history, when relevant
Invoices or sales records
Gallery or consignment documentation
You don’t need expensive inventory software to begin.
A spreadsheet, organized digital folder, and consistent artwork numbering system can already create a useful paper trail.
And remember to keep a backup somewhere other than only on the computer sitting in your studio.
Your Photographs Matter Too
Photograph finished artwork before it leaves your studio.
For three-dimensional work, take several views. For installations or complex mixed-media work, document individual components as well as the completed installation.
Save the files using your artwork inventory number rather than names such as:
IMG_4837.jpg
A file called:
2026-014_BlueMorning_Front.jpg
will be much easier to identify years later.
These records can help not only with insurance questions, but also with exhibitions, galleries, your website, taxes, estate planning, and your own artistic archive.
When Should You Consider Talking to an Insurance Professional?
No single dollar amount applies to every artist.
But it may be time for a conversation when:
your collection of unsold work is becoming financially significant;
you regularly sell your work;
customers or collectors visit your studio;
you frequently ship or transport artwork;
You participate in exhibitions and art fairs;
galleries hold your work on consignment;
you have expensive equipment or materials;
or replacing your studio inventory after a major loss would be financially difficult.
The goal isn’t to buy every type of insurance available.
The goal is to understand your actual risks and what your current policy does and does not cover.
One Small Step You Can Take Today
You don’t have to solve all of this today.
Start with one simple project.
Open your artwork inventory and make sure every finished piece has:
a number + a photograph + a description + a value/price record + a location.
If you don’t have an inventory yet, start with your ten most valuable or important pieces.
Then contact your insurance agent and ask:
“I am a working artist, and I keep artwork that I create for sale in my home studio. How does my current policy cover my finished artwork, supplies, equipment, and artwork when it leaves my home?”
That one question may tell you far more than simply looking at your policy’s total personal-property limit.
Protect the Work Behind the Work
Artists spend countless hours creating work but often very little time documenting what they have created.
Insurance cannot replace the creative process behind an original piece.
But good records, combined with appropriate insurance when needed, can help protect the financial side of the work you have spent years building.
Your inventory isn’t just a list of objects.
It is a record of your creative history.
And that is worth protecting.
Disclaimer: This article is for general educational purposes only and is not insurance, legal, tax, or appraisal advice. Insurance policies, coverage, valuation methods, and appraisal requirements vary by insurer, policy, location, and individual circumstances. Consult a qualified insurance professional or appraiser regarding your specific situation.


Leave a comment